 I always read on a daily basis about Loan Modifications, Short Sales, Foreclosures, and the like. I read alot of information and from what I am seeing, as general consensus, Lenders have been helping alot of people with whatever mortgage relief that is deemed necessary by the lender. According to what http://www.dsnews.com says, in the month of May, there were 63,000 permanent solutions for homeowners in default. Of that 63,000, there were 17,590 of those homeowners that were made complete by President Obama's HAMP program. By all means, these numbers are great. When Wells Fargo accounts for 11,000 of those modifications alone, it seems to be looking up for the homeowner. My problem with this is that I speak to alot of people throughout the day, and I am wondering why the majority of these people have not been helped. see the majority of my clients, or potential clients have been trying to get loan modifications, even for the trial period for 7-12 months. Those that are longer than that have flat out been denied and the lender is speaking of private investors not willing to budge. In some cases this may be true, but I will bet my last dollar that 90% of those cases are not. See the problem is very simple. People need help. Homeowners are defaulting on loans that they couldn't afford in the first place and they become complacent once they hit a certain time frame that they have defaulted and the bank as not acted. There is approximately 2.53 million homeowners in default currently and that has been close to the same number since 2009. So while the lenders are supposedly "helping", there are just as many people that are looking for answers at the same time. Foreclosures are still up. According to HOPE NOW, there was a rise in forecloses from the month of April (60,000) to May (65,000). what this tells me, is that lenders are willing to put more people on the street than they are looking to help. I say this ignorant to the individual situations, however I speak with or meet hundreds of people a day that are in dire straits and need help so I think that I can speak for the majority of folks when I say that it isn't enough.
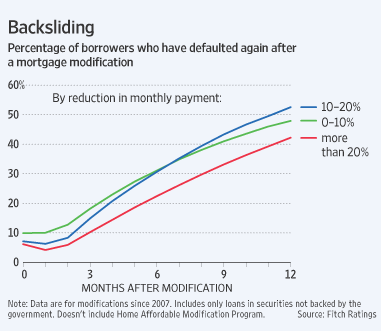
Bi- Partisan settlement that has come into play leaves the Big 5 having to give out 125 Billion in relief in a matter of 3 years. This is a large amount of relief. My issue with this is that the big 5 are going to hold out as long as they can to offer this assistance and the foreclosure rate is going to continue to go up unless the state officials do what California did and make it a law that lenders may not foreclose while in some sort of relief program. This is a great law for those that will be approved for the relief program, but what about the ones that are "not qualified", I see these lenders denying any relief after going through the motions, and escalating foreclosure. Believe you me, these machines are debt collectors and I think we homeowners are thinking incorrectly if we think that they are out for our best interest. they may offer some form of relief to some of us in this 3 years, but it is going to be on their terms, which can increase your payments, balloon the payments for any relief that they are putting on paper and still put you in a bind, and ultimately line their pockets with money of the struggling. Look at it this way, marketwatch.com expresses that 56% of people that get their loan modified permanently, a going back into default in an 8 month time period.
I know that this is a personal rant of mine and i apologize if you feel it too "opinionated". However I am writing on behalf of the clients that I deal with on a daily basis and offering this opinion based on what I have to do to keep people in their homes on terms that are beneficial to them and not the lender.
Please comment or email me if you have questions, or concerns.
